The servicing layer your lending platform needs. From first EMI to final receipt.
Custom EMI schedules, charge & penalty engine, three-channel EMI collections, prepayment & restructuring, borrower statements, and DPD tracking, built for the operational reality of running an NBFC book, with the audit trail your finance team needs.
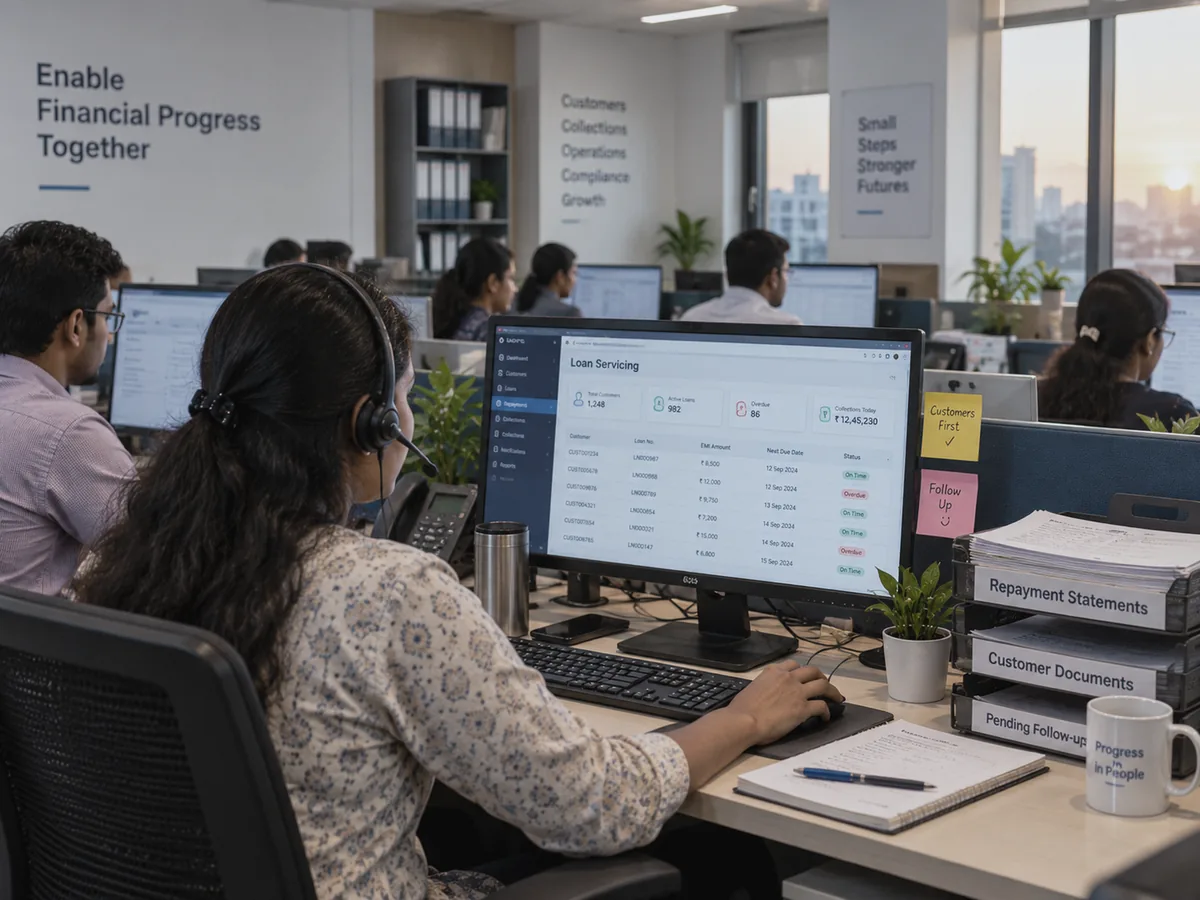
Ten servicing modules, wired for downstream consumers.
Each module emits events that collections and pricing subscribe to in real time. No batch-job lag, no stale snapshots. And none of it is written for a single financial product, a new one is defined as configuration, with its own schedule, fee and charge behaviour.
Reducing balance, flat, bullet, daily, custom. Holiday calendar awareness.
Pre-EMI, late, bounce, foreclosure, restructuring fees. Tax-aware.
DPD bucket transitions, IRAC norm classification, real-time event stream.
Partial / full prepayment, term changes, EMI re-amortization, COVID-style relief plans.
Account, repayment, interest certificate, foreclosure letters, branded, multilingual.
Postings land in the platform's own ledger first, then flow out to Tally, BUSY, or a custom ERP. The onward integration is engagement-scoped per client.
eMandate auto-debit presented on the due date, QR or payment link on failure, cash with a sequenced receipt. Payment before due, part, full and excess payment each handled on their own terms, with DPD updated per event.
Every state change is sealed into a cryptographic chain with periodic integrity checks, carrying who acted and in what role. Altering a past record is not merely against policy, it is detectable, and an auditor can verify the chain themselves.
Each loan carries the product, fee, and policy setup in force on the day it was sanctioned. A rate change today cannot rewrite a loan booked last month.
Double-entry journals that must balance before they post, accounting periods that lock, and a second approver on every manual entry, so the books close without an export step.
Collections, built for how repayment actually happens.
A collections queue is the easy half. The work is in the payment that arrives early, the one that arrives short, the one that arrives twice, and the correction someone has to make afterwards without quietly rewriting the money trail.
- EMI presented on the due date against the live mandate, with every presentation and retry logged
- Bounced auto-debit re-presented on schedule, with a QR or payment link sent as the fallback
- Payment before the EMI falls due, handled on its own terms rather than forced into the next instalment
- Full payment, part payment, and excess payment each recomputed correctly against the schedule
- Foreclosure quoted, collected, and closed with charges applied per product configuration
- Write-off processing with the approval chain retained for inspection
- Penal charges raised automatically on the events that trigger them, tax-aware
- Bounce charges applied per product and reflected on the borrower's statement
- Cash collection captured in the field, with the collecting officer and deposit tracked to the bank
- A sequenced receipt issued on every collection, cash or digital, at the point of collection
- Fee and charge changes, collection corrections, and deletion of a cash entry all need a second approver
- DPD updated per collection event, not on a nightly batch, with channel-wise and bucket-wise reporting
Built into the systems your finance and ops teams already run.
One version of the truth, across your LMS and the regulator.
An LMS that calculates NPA only for the regulator's report is already broken. We make NPA a first-class event with downstream consumers subscribed in real time.
Bucket transitions emit downstream events to collections and pricing, not just a regulator report.
Sub-standard / Doubtful / Loss classification with the evidence trail RBI inspectors expect.
Granular role-based entitlements, DPDP-aligned consent management, and PII encrypted at AES-256-GCM at rest and in transit.
Every view, download, and export of personal data is recorded with the person, their role, their IP, and how many records they pulled. A DPDP question is answered by running a query, not by opening an investigation.
DPD-triggered notifications respect grievance redressal SLAs and DPDP consent. No unsolicited contact outside the borrower's recorded preferences.
Servicing modernization without halting collections.
- Replace legacy LMS while live collections continue uninterrupted
- Migrate per loan product, not big-bang
- Mirror NPA classification to legacy + new for one cycle
- Audit-ready archival of legacy LMS once sunset
- Production support with senior engineers, not L1 ticket queues
NBFC LMS, what buyers ask before scoping.
Real-time NPA, IRAC classification, restructuring depth, audit retention, sequenced migration.
How does "NPA as a first-class event" actually work in production?
Every EMI event (payment, partial, bounce, restructure) emits an NPA-evaluation trigger and the classifier runs. State transitions (Standard → SMA-1/2 → NPA → Sub-standard → Doubtful → Loss) emit domain events with timestamp and evidence. Collections, GL, comms and pricing subscribe, not stale snapshots.
What restructuring scenarios are supported out-of-the-box?
Twelve at MVP: partial prepayment with re-amortisation, full prepayment within cooling-off, term extension with provisioning recompute, rate revision mid-term, holiday add (moratorium), EMI date change, co-borrower add/remove, top-up linkage, renewal with revised terms, OTS with write-off, NPA recalibration, automated comms per scenario.
How does the LMS integrate with our existing GL (Tally, BUSY, SAP)?
Postings land first in the platform's own double-entry ledger, then flow outward. T+0 event-driven posting. Sub-ledger reconciliation native. NACH bounce auto-reverses. Restructuring auto-posts with provisioning recompute. Period close becomes a T+1 event-completion check, not a multi-day reconciliation marathon. Adapters pre-built for Tally, BUSY, SAP, Oracle Financials, and QuickBooks.
How long is audit data retained, and is it queryable?
The per-loan audit trail retains all state changes per RBI policy (10+ years), each one sealed into a cryptographic chain with periodic integrity checks, so tampering is detectable rather than merely forbidden. Queryable per loan, customer, portfolio. Replayable to reconstruct any historical state, when an inspector asks why a loan was NPA on a given date, you answer in seconds, not via engineering archaeology.
Can we migrate from our existing LMS without halting collections?
Yes. Same sequenced migration as LOS. Run batch and event-driven NPA classification in parallel for a month. Diff outputs daily. When divergence across all bucket transitions is zero, switch consumers (collections, GL, comms, pricing) one at a time. Decommission the batch classifier after two close cycles.
Is the LMS suitable for a ₹100Cr–₹1,000Cr AUM NBFC, or does it scale further?
Engineered for ₹100Cr–₹5,000Cr AUM. Above ₹500Cr, event-driven NPA is unambiguous, collections is making decisions on stale data that costs recovery. Architecture is cloud-native and designed for 10x AUM growth without re-platforming.
If your LMS computes NPA in a batch job, you're operating two versions of the truth.
The fix isn't a new dashboard. It's making NPA a first-class event in your LMS, with downstream consumers subscribed in real time. Talk to a senior engineer.
- A senior engineer reviews your submission, not a sales rep
- Response within one business day
- NDA available before scoping if needed
Ready to talk? Schedule a 30-min call with a senior engineer.
Pick a time that works for you on our booking page. Bring your domain pain points, regulatory posture, and integration list — we'll map a sequenced delivery path.